Condor blog
Insights and practical guidance for modern clinical finance teams.
Leading biopharma R&D teams rely on Condor

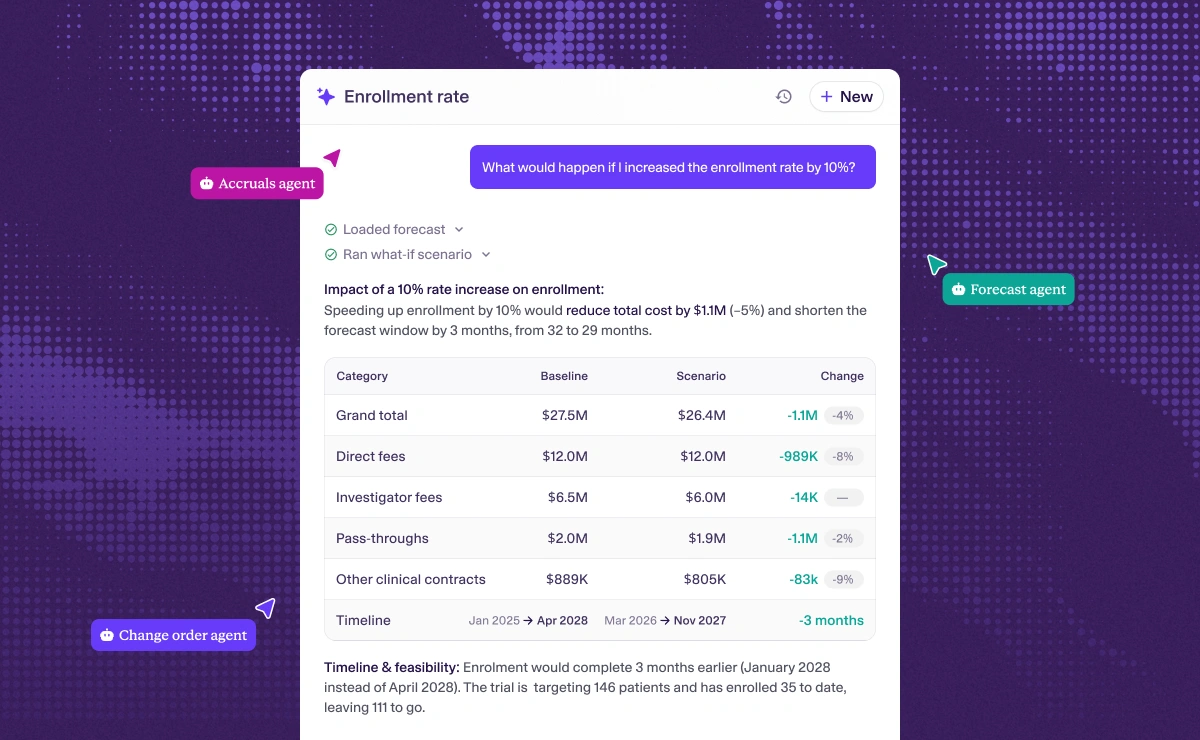
Today we unveiled Condor's Clinical Finance AI Agent — the world's first AI agent purpose-built for biopharma R&D finance.
Ask it why a trial's actuals and forecast diverged, and it reasons across your full budget and forecast history to give you the answer in seconds, not the days it takes to reconcile across your ERP, CTMS, EDC, and a dozen spreadsheets. Ask it what a change in site mix or enrollment timing will cost you, and it runs the scenario and builds the resulting model directly in Condor. It doesn't just surface a number. It gives you the "why," and then it does the work.
This is a big milestone for our company and industry. It's also the moment I've been building toward since the day I started Condor.
The vision I had five years ago
When I founded Condor, I believed the financial machinery underneath every clinical trial could be fully automated, end-to-end, with AI reasoning on top of it.
No more manually managing or outsourcing your finances. The numbers, built by an engine you can trust. Workflows run by AI. The why behind the numbers, uncovered in seconds instead of weeks, while there’s still time to act.
Our new agent is the realization of that vision.
Why it took five years
Building AI that produces numbers you can actually trust is unbelievably hard.
It took building Condor's financial engine first — a deterministic layer that follows defined rules, produces consistent output every time, and is fully auditable. No guessing, no black box, no "the model thinks it's probably right." Every number has to tie back to the clinical activity that actually drove it, because in this industry, a number nobody can defend is a number nobody will use.
It took building a knowledge graph grounded in a clinical and financial ontology we developed over years of work with Big 4 accounting firms — mapping how budgets, vendor contracts, clinical sites, and clinical activity actually connect to each other, across hundreds of studies and therapeutic areas. That ontology is what lets our agents understand a change order or a forecast variance the way a clinical finance team does, instead of the way a generic model guesses.
We built all of that first, five years ago, before there was a market pulling us to do it, because we knew it was the only foundation AI could stand on and still be trusted with a number that ends up in a board deck.
Recently, competitors that built their entire business model around outsourcing clinical finance — putting bodies behind the work instead of automating it — have realized AI is where our industry is headed. They're years behind, so the best they can offer is AI bolted on top of their services model.
Layering AI onto a services model doesn't change what the AI is standing on. If the underlying data was never built for automation — if it was always meant to be assembled by a person — AI on top of it can move faster, but it can't reason with the same grounding as our AI platform. It will take those companies years to build what we have been building for the last five years, because an ontology and a knowledge graph like ours can't be retrofitted. They have to be the starting point.
Why our AI platform matters now, more than ever
For most of the last century, science was the bottleneck in drug development. AI is closing that gap fast, and pipelines are about to fill with more candidates than this industry has ever had to fund at once. Every one of those candidates still has to be forecasted, funded, and managed. Right now, the financial infrastructure doing that job is still, for almost everyone, a spreadsheet.
The bottleneck didn't disappear. It moved from the lab to the ledger. Today, Condor is the only platform built from the ground up to run biopharma R&D finance and operations at the scale AI-driven pipelines are about to demand. Because we built the engine, then the knowledge graph, then the agents, in that order, on purpose.
What comes next
Our Clinical Finance Agent is one of a growing team of agents built on Condor's knowledge graph. Each one, including our forthcoming investigator grant agent, is purpose-built to remove a specific piece of manual work slowing R&D finance and clinical operations teams down.
My vision is here: No more manually managing your finances. The numbers built by our engine. The workflows run by AI. The why behind the numbers uncovered in seconds, not weeks, while there’s still time to act.
This is the start of something big for our industry.
If you want to see the agent for yourself, book a demo.
Recent posts
The Cost of Saving Lives Shouldn’t Be a Mystery
Today, I'm proud to share that Condor Software has closed a $24 million Series A funding round, led by Insight Partners, with participation from Felicis, 645 Ventures, Pamir Ventures, SNR Ventures, Prebys Ventures, and Bramalea Partners.
Every therapy that reaches a patient is a miracle of science and resilience without financial clarity. Most people involved in therapies focus on science. I focus on finance, and what happens when it breaks down.
Earlier in my career, I worked alongside teams bringing treatments to patients who had run out of options. I watched what it meant to families (including my own), to clinicians, and to entire communities when a therapy worked. I was on the inside, building the accounting workflows the pharmaceutical industry uses to manage clinical trial finances. What I saw blew my mind: organizations managing billions in R&D spend on spreadsheets stitched together late at night. Critical decisions about which therapies move forward, made on data that was fragmented, manually reconciled, erroneous, and months out of date.
Good science was being crushed by broken financial infrastructure. This shouldn’t be the case, and I knew I couldn’t let this continue. So I founded Condor.
A lot has changed since I founded the company five years ago. Our team has grown. Our platform has matured into the first ever AI-powered financial intelligence layer purpose-built for life sciences. And some of the world's most innovative biopharma organizations — like Acadia Pharmaceuticals, Alumis Therapeutics, BridgeBio Pharma, and Madrigal Pharmaceuticals — now rely on Condor to manage over $19 billion in R&D spend.
What hasn't changed is our mission: to empower biopharma teams to see, predict, and control the cost of bringing life-changing therapies to patients. And our mission has never been more urgent.
AI is completely transforming human health, drug discovery, disease prevention, and the way we treat, cure, and care for people. But here's the uncomfortable truth nobody's talking about: the future everyone's envisioning can't actually happen yet. Not because the science isn't ready. Not because the data isn't there, but because the financial infrastructure that has to support it all is broken.
The life sciences industry spends $300 billion a year on R&D. Today, most of that is trapped in spreadsheets, PDFs, and disconnected systems. That is the choke point. That is what's standing between the world we have and the world we're all trying to build.
Condor exists to remove that choke point. We give CFOs, clinical executives, and R&D leaders something the industry has never had: a living, breathing financial command center. The ability to see in real time where every dollar is going, how trials are performing, and where to reallocate and accelerate. It’s all made possible by our platform’s proprietary clinical and financial ontologies that map the relationships between trial protocols, site-level activity, vendor contracts, and accounting rules. The platform’s knowledge architecture was developed over years with Big 4 accounting firms and embedded in audit-grade workflows.
What gets me and everyone at Condor out of bed every morning is witnessing accounting, FP&A, and clinical operations teams have that “aha moment” when they turn on our platform. For example, the CFO of a growing biotech told us recently that for the first time she could see exactly where her clinical trial dollars were going. No spreadsheets stitched together late at night. No uncertainty heading into board meetings. Just a clear, trusted view of trial spend, forecasts, and risk. She told me, “For the first time, I feel like we're making strategic and proactive decisions instead of explaining surprises.”
That shift from reactive to proactive is everything. Better visibility leads to better decisions. Better decisions drive better outcomes. And better outcomes mean more therapies reach the people who need them.
We aren’t building accounting software or a reporting tool. We’re building the infrastructure for how the industry funds innovation itself. Every drug discovered by AI, every molecule modeled, every trial run more efficiently — that future flows through financial infrastructure. Condor is building that infrastructure. This Series A gives us the resources to go further by expanding our platform, deepening our enterprise capabilities, and growing the extraordinary team that will carry this vision forward.
Thank you to our customers for trusting Condor, our team for its unmatched expertise and resilience, and our investors for believing in what’s possible. Together, we’re building the AI-powepred Financial Intelligence Platform that is helping bring life-changing therapies to patients faster.
This vision is worth fighting for. And together, we're proving it.
— Jen
Read the article
Outsourced R&D, In-House Accountability: How to Stay Compliant
Biotech companies rely on outsourced research and development (R&D) to speed innovation, access specialized expertise, and control costs. However, accounting for these outsourced activities, particularly clinical trial accruals, presents challenges that demand financial oversight and strategic planning.
Emerging life sciences companies often engage multiple Contract Research Organizations (CROs) for clinical trials, each with distinct contracts, payment structures, and invoicing schedules. As trials progress, finance teams must track service milestones, estimate unbilled services, and ensure accurate financial reporting. Getting this right is essential for compliance with U.S. Generally Accepted Accounting Principles (US GAAP) and for making sound business decisions.
Clinical Trial Accruals Must Be Accurate to Ensure Financial Integrity
Clinical trial accruals are one of the most complex areas of biotech finance. Companies must record expenses as they are incurred, even before invoices arrive. This means estimating the cost of services delivered but not yet billed—a task complicated by differences between invoicing terms and actual service delivery.
For biotech firms running multiple trials, the challenge is even greater. They must juggle various CROs, manage multiple agreements, and maintain precise records of trial progress. Errors in these accruals can lead to financial misstatements, eroding investor confidence and, in some cases, requiring restatements.
Accurate Accruals Require the Right Methods, Sound Assumptions, and Reliable Data
Accurate clinical trial accruals depend on a few essential elements:
1. Choosing the Right Methodology
Finance teams use different methods depending on the complexity of the trial and the contract structure. In particular, contracts with CROs often fall into three categories:
- Direct Service Fees – Costs tied to specific units of work or milestones.
- Investigator Fees – Payments to trial sites and patient costs.
- Pass-Through Costs – Expenses incurred by the CRO on behalf of the biotech company.
For small Phase 1 trials, milestone-based or timeline amortization methods often suffice. For larger, later-phase trials, companies may need more detailed tracking methods based on patient enrollments, site activations, and study timelines.
2. Establishing Sound Assumptions
Since estimates are forward-looking, finance teams must base them on solid assumptions, such as:
- Expected patient enrollment and site activations.
- Trial duration and expected protocol changes.
- Cost per patient and site.
Close collaboration between finance and clinical operations is essential to refining these estimates.
3. Ensuring Data Accuracy
Reliable accruals require timely and comprehensive data, including:
- Patient visit records and trial procedures.
- Milestone progress reports.
- Contract amendments and invoices received.
Maintaining an integrated data management system that centralizes this information improves financial accuracy and efficiency.
Recognizing these key factors is crucial, but companies must also take actionable steps to improve financial reporting and compliance. Implementing best practices can help finance teams navigate these complexities and create a structured approach to clinical trial accruals.
Strengthening Financial Oversight in Outsourced R&D Requires a Structured Approach
To navigate the complexities of outsourced R&D, biotech companies can use this checklist to ensure financial accuracy and compliance:
✅ Establish Clear Accounting Policies
- Do we have standardized accounting policies specific to outsourced R&D activities?
- Are the methodologies for estimating and recording clinical trial accruals clearly defined?
- Are similar outsourced R&D activities accounted for consistently?
✅ Align Internally Before Engaging Vendors
- Have finance, clinical operations, and procurement teams aligned on key financial reporting needs?
- Have internal teams set clear expectations on data collection and reporting deadlines?
- Are roles and responsibilities clearly defined for managing vendor financial data?
✅ Review Key Contract Terms
- Do we fully understand the payment structures and milestone agreements in CRO contracts?
- Are budget assumptions clearly outlined and aligned with financial forecasts?
- Have we reviewed contracts to ensure all financial obligations are captured accurately?
✅ Foster Cross-Functional Collaboration
- Do finance and operational teams communicate regularly to discuss trial progress and financial projections?
- Is there a structured process for sharing real-time updates on cost changes, site activations, or enrollment fluctuations?
- Are clinical and finance teams aligned on trial timelines and budget adjustments?
✅ Regularly Review Assumptions
- Are we periodically reassessing key financial assumptions?
- Do our accrual estimates reflect the latest updates on patient enrollment, site activations, and costs?
- Are there processes in place to adjust financial projections based on evolving trial conditions?
✅ Implement Strong Monitoring and Controls
- Are we reconciling invoices against services provided and accrual estimates regularly?
- Do we have tracking mechanisms to verify the accuracy of financial reporting?
- Are we maintaining a system to document all financial changes and contract modifications?
By following this checklist, companies can ensure that they have a structured approach to managing outsourced R&D accruals while maintaining compliance with US GAAP and fostering financial transparency.
Financial Discipline in Outsourced R&D Drives Long-Term Biotech Success
Outsourced R&D is critical to biotech innovation, but it brings financial challenges. By implementing strong accounting policies, refining assumptions, improving data accuracy, and fostering cross-functional collaboration, companies can navigate these complexities and maintain compliance with US GAAP.
In the biotech industry, financial transparency is as important as scientific progress. A disciplined approach to managing outsourced R&D accruals ensures financial health, investor confidence, and long-term success.
Read the article
Managing Upfront Payments: From RFP to Reconciliation
In clinical trials, Contract Research Organizations (CROs) often request upfront deposits or retainers for various expenses. These deposits, though common, are sometimes overlooked during contract negotiation. However, understanding and monitoring these amounts can save your company significant money and prevent cash from being unnecessarily tied up in the study. Large upfront payments are effectively interest-free loans to the CRO—it’s essential to manage them wisely.
Types of Upfront Payments
- Direct Fees
- Purpose: These upfronts are used to manage cash flow and float CROs for services they perform, usually under unit-based contracts where payment is made in arrears.
- How it works: The deposit is held until the end of the study and credited back toward final invoices as services near completion. The amount of the deposit can fluctuate with changes in the trial budget when a change order is executed—additional upfronts may be requested when the budget grows. Similarly, reduced upfronts are possible when services are downscoped. If you have a change order where the services budget is reducing, you should request a reduction to the deposit as well!
- Key Insight: Because these upfronts are used for a measurable purpose, to manage cash flow and float the CRO, it’s very easy to gauge the reasonability of the upfront being requested using a simple formula: (Total CRO Services Budget÷Contracted Days)×(1 month+payment terms)
- For a $1M budget over a 2 year timeline (730 days) with 30 day payment terms (60 day float), the required upfront should be $84,269.
- Pass-Through Costs
- Purpose: These upfronts cover start-up costs for third-party vendor contracts managed by the CRO and also as a float for all other pass through costs incurred by the CRO.
- How it works: The portion of the deposit related to vendors is typically applied to the first few invoices pertaining to third-party vendors managed by the CRO. The remaining deposit pertaining to all other pass through costs are either:
- Held until the end of the study, similar to the Direct Fees upfront, or
- Amortized—with an equal portion drawn down and applied to each pass-through invoice over the study's duration.
- Key Insight: Ensure that the portion of upfront payments related to third-party vendors is limited to true upfront costs. CROs, being risk-averse, may attempt to secure a larger portion of the third-party vendor budget in advance. However, most vendor agreements, such as EDC contracts, should be amortized over the full duration of the trial—paying the entire amount upfront is usually unnecessary.
- Investigator Grants/Site Payments
- Purpose: These rolling deposits cover patient fees and site-related administrative costs.
- How it works: Replenished on a typical cadence, usually quarterly, they ensure cash flow is maintained for site payments.
- Key Insight: CROs may request inflated amounts to maintain a cash buffer for unforeseen site expenses. In more extreme cases, they might propose a blanket deposit without conducting a proper analysis to determine its reasonableness, leading to funds being held unnecessarily for months, or even over a year. It’s crucial to evaluate whether the requested upfronts are justified and align with projected enrollment and protocol costs.
Key Considerations
- When Are Upfronts Applied? Upfronts can be applied to initial invoices, held in escrow, or reserved for the trial’s conclusion.
- Communication with Vendors: Open communication ensures upfront management is transparent and aligned with expectations.
- Final Reconciliation: CROs should reconcile and apply any remaining upfront balances to final invoices before closing out the study. Tracking this ensures CROs remain accountable and don't profit from retained upfronts.
By thoroughly understanding and managing upfront payments, you can prevent unnecessary financial strain, ensuring your funds are allocated where they’re truly needed throughout the clinical trial.
Read the article
Optimizing Clinical Trial Finance: Best Practices for Collaborating with your CRO
In the rapidly evolving landscape of biotechnology, collaboration with Contract Research Organizations (CROs) is essential for successful clinical trials. However, it does not come without risk: upfront investment, hidden costs, and misaligned financial priorities to name a few. Effective financial management is crucial to ensure timely and accurate project execution, as well as audit preparedness. Here are best practices to enhance your partnership with CROs and optimize your clinical trial finances.
1. Establish Clear Contracts and Set Expectations
Define specific financial deliverables, timelines, and performance metrics in your vendor contract to avoid misunderstandings. Discuss expectations for reporting early to ensure continuous and timely flow of information throughout the study.
2. Regular Financial Reconciliation
Ensure frequent reconciliation between the CRO’s reported costs and your internal financial records. This helps prevent discrepancies and ensures that financial reports remain accurate and audit-ready.
→ Essential Reporting for Financial Health
To maintain optimal financial oversight when working with your CRO, ensure you have access to the following critical reports:
CRO Unit/Work Completed Tracker
- Require detailed, line-item level tracking from your CRO for direct fees (regardless of fixed-price or milestone-based contracts), along with transaction-level tracking for pass-through and investigator fees.
- Milestone payments do not accurately reflect the work completed, but rather are a tool for cashflow management. A comprehensive tracker for direct fees, pass-through costs, and investigator fees ensures transparency and alignment with the CRO’s estimate of expenses incurred, and will be required by auditors.
- Reporting should be monthly or quarterly, in alignment with your financial reporting cycle, and include a detailed task-by-task breakdown of units performed by the CRO.
Subject Visit Report
- Track patient metrics: screenings, enrollments, active participation, and completions.
- Use this data to accurately estimate investigator grants and verify CRO invoicing, especially for site and patient-related payments.
Additional Support Reports
- Screen Failure Report: Insight into patient drop-off rates.
- Unscheduled Visits Report: Track unexpected patient interactions.
- Invoiceables/Procedures Report: Ensure all billable activities are accounted for.
Site Listing
- Monitor recruitment, activation, and closure of study sites.
- Independently verify CRO reports to validate milestone payments.
IMV Report
- Assess your CRO’s monitoring activities and their completion status.
- Cross-reference this data to ensure accurate invoicing.
3. Collaborate on Budget Forecasting
Work closely with the CRO and other internal teams to develop accurate, realistic budgets, and update forecasts regularly. Integrating real-time data from both the CRO and internal teams can help monitor and adjust for any unexpected costs.
4. Use Integrated Financial Tools
Leverage financial software platforms that support real-time data exchange, automated accruals, and compliance tracking. This reduces manual errors and keeps finance teams aligned with clinical progress.
5. Establish a Communication and Reporting Cadence
Establish regular check-ins and reporting schedules with the CRO to stay updated on trial progress and financial impacts. Regular updates can prevent last-minute budget surprises and align the CRO’s work with financial goals.
→ Why an Invoice Isn’t Enough
CRO invoices are notoriously opaque. It is not uncommon to receive a multi-million dollar invoice with a single line item: Project Management.
To safeguard your finances:
- Request Line-Level Detail: During the study start-up and work order negotiation, ask for detailed reporting before invoicing. This helps confirm expenses against your independent, activity-based estimates.
- Leverage Real Study Data: If there are discrepancies, use your detailed expense estimates to discuss variances with your CRO.
6. Define Risk Management Protocols
Plan for potential cost overruns and delays by building contingency funds and risk management strategies into the budget. This ensures financial flexibility when dealing with unexpected clinical outcomes.
Avoid the black box, and be proactive in managing change orders to prevent unexpected costs and surprise retrospective invoices:
- Identify Hidden Costs: Watch for price increases, volume changes, mistakes, and duplicate items.
- Perform Line-Level Comparisons: Analyze your current work order against any upcoming changes. Use tools like specialized software to simplify your review.
- Validate New Additions: Ensure any new line items are indeed necessary and avoid unnecessary duplication.
Conclusion: Trust but verify
Navigating the complexities of clinical trials requires a strategic approach to financial management, especially when partnering with CROs. Establishing clear contracts, maintaining robust financial oversight, and fostering open communication, allows clinical finance organizations to enhance collaboration with CROs and mitigate financial risks. By prioritizing transparency and proactive planning, you can ensure that your partnership with CROs not only meets your financial goals but also supports the broader mission of advancing innovative therapies.
Read the article
Stop Straight-Lining, Start Scaling: The Key to Faster, More Accurate Accruals
Clinical trials are among the most complex financial endeavors in biotech, requiring careful financial planning, tracking, and reconciliation. Ensuring accurate financial reporting and vendor accountability means answering three key questions: What do we expect to happen? What has actually happened? And what is driving the variance between expectations and reality?
The Challenge of Forecasting Clinical Trial Costs
Unlike other industries where cost forecasting follows predictable patterns, clinical trials introduce many unpredictable variables. Enrollment rates, protocol amendments, and site-specific costs can make standard financial tools ineffective. Forecasting must be dynamic, aligning cost distributions with actual clinical drivers rather than relying on broad assumptions.
Accrual accounting—determining costs incurred but not yet paid—is another essential component. Many companies still rely on spreadsheets to manage this process, but doing so often leads to inefficiencies. When data is delayed or inaccurate, finance teams must choose between speed and accuracy, a trade-off that can complicate compliance and financial reporting.
The Pitfalls of Straight-Lining Costs
One common but problematic approach is straight-lining costs—spreading expenses evenly over time. While this method may seem simple and efficient, it often leads to major financial and compliance issues. Inaccurate accrual estimates can trigger audit misstatements, requiring time-consuming adjustments and increasing the risk of financial restatements.
A better alternative is to use activity-based accruals and multi-source triangulation—leveraging multiple data sources to validate costs. This approach provides a more accurate picture of clinical trial expenses and enhances financial reporting. While implementing an automated accrual system requires upfront effort, the long-term benefits include faster close times, improved audit readiness, and reduced financial risk.
Case Study: Ventyx’s Transition to Automated Accruals
Ventyx, a leading biopharmaceutical company, faced significant inefficiencies in their R&D accrual process. Heavy reliance on CRO reporting and manual processes led to long close cycles, frequent audit adjustments, and budgeting challenges. Managing multiple Phase 1 and Phase 2 trials further complicated financial forecasting.
By adopting an automated accrual platform, Ventyx reduced their monthly close process by 78%, completing it in under a week. The impact was significant:
- Efficiency: Faster and more reliable accrual processing.
- Accuracy: Fewer post-close adjustments and better compliance.
- Collaboration: Improved communication across finance, FP&A, and clinical operations.
- Vendor Management: Enhanced visibility and stronger contract negotiation capabilities.
- Audit Readiness: Strengthened SOX compliance and reduced audit-related inquiries.
As Roy Gonzales, Senior Vice President of Finance at Ventyx, stated:
"Previously, our close process spanned between 3 to 4 weeks and heavily relied on our CRO. Our new system enabled us to streamline our monthly close process, cutting it down to under a week."
Ventyx’s experience underscores a crucial point: organizations don’t have to choose between speed and accuracy. By leveraging automation, they can achieve both.
The Role of Automation in Clinical Trial Financial Management
As clinical trial portfolios grow, managing financial reporting manually becomes unsustainable. Automation bridges the gap between finance, accounting, and clinical operations by:
- Integrating vendor contracts, change orders, and out-of-scope costs in real time.
- Ensuring forecasts and actuals remain aligned.
- Providing structured data that enhances transparency and decision-making.
Organizations that invest in automation transition from reactive financial management to proactive strategic oversight. By removing inefficiencies and enhancing data accuracy, finance teams can support broader business objectives more effectively.
Final Thoughts
Clinical trial financial management requires a delicate balance between efficiency and accuracy. While straight-lining costs may seem like an easy solution, it often creates more problems in the long run. Investing in automation, adopting multi-source triangulation, and aligning finance with clinical operations can ensure long-term financial stability.
The takeaway is clear: accurate, fast, and compliant accruals are not mutually exclusive. By making the right investments, biotech companies can streamline operations and gain greater financial control.
Read the article
Clinical Trial Reconciliation Best Practices
Clinical trials often involve complex, high-value contracts that require reconciliation as the trial nears its conclusion. With varied payment structures and contract terms, it’s crucial to understand your obligations to ensure that the final reconciliation is transparent, accurate, and fair for both parties.
Know Your Contract
Understand the Payment Structure
- Unit-based: Vendor bills monthly for work completed.
- Time and Materials: Vendor bills monthly for hours worked and associated costs.
- Milestone-based: Vendor bills a percentage of the contract value upon reaching key milestones (e.g., Last Site Activated, Last Patient In, Database Lock).
Considerations for Early Trial Termination
Minimize Carrying Costs: Immediately stop unnecessary activities (like meetings) after trial cancellation to avoid additional billing.
Blended Line Items: Review blended line items that include multiple activities to ensure they match actual trial activities.
- Monthly management units that require varying levels of effort throughout the trial are impacted most by this
- Project Management
- Clinical Team Management
- Meeting/Teleconference line items
- Usually include varying attendees required throughout the trial timeline
- Other common line items impacted
- Regulatory submissions
- ICF related units
- Database Migrations
- Protocol Amendments
- Minor vs. Major
Milestone Contracts: If milestones were not met, ensure vendors report actual work completed, not just based on invoices.
Additional Considerations
- Upfront Retainers: Track retainer balances in invoices and understand when they are drawn down and replenished. See the “Managing Upfront Payments” resource for details.
- Bonus/Penalty Clauses: Be clear about any contract clauses that could affect final costs or result in credits.
- Inflation Clauses: Clarify how inflation adjustments are calculated, especially if the trial timeline shifts.
Reconciliation Overview
The reconciliation process is the same across payment structures:
Total Cost Incurred −Total Amount Paid = Final Reconciliation Value
- Total Cost Incurred: The final contract value determined by the vendor and agreed upon by the sponsor.
- Total Amount Paid: All payments made to the vendor to date.
Documents to Request for Reconciliation
To confirm Total Costs Incurred, request:
- Final Budget with a detailed line item breakdown.
- Unit Tracker showing completed tasks by month.
- Record of all pass-through transactions and site payments made by the vendor.
- Site Listings: Includes recruitment, activation, and deactivation dates to validate site-related budget items.
- Final EDC Reports:
- Subject Visits Summary: Confirms patient visits by site.
- Invoiceable Reports: Verifies invoiceable activities.
- Final Visit Report: Tracks patient activity and final visits, useful in early trial shutdowns.
- Monitoring Visit Listings: Compares completed visits to the budget.
- Independent Expense Estimates: Use real trial data to assess the reasonableness of the final contract value.
To confirm Total Invoices Paid, request:
- Vendor-provided invoicing summary of all invoices sent and received payments.
- Internal invoicing summary of all payments made to the vendor.
Software Tools
- Clinical Trial Finance and Accounting Software: Newly adopted technologies that utilize real clinical trial data in tandem with all of the vendor contracts to produce a defensible estimate of trial spend in relation to the contracted terms. This provides a reasonability check against the final contract value the vendor is requiring.
- Investigator Grants Payment Software: Provide more clarity into what is being invoiced from each site and enable a more streamlined payment process.
- Automated Invoicing Software: Some ERPs are equipped to support automated invoicing with your vendor to provide transparency and alignment of all transactions, enabling a clear understanding across parties of the invoicing position per contract.
Benefits to Software Tools
- Automated workflows enable swift decision making and ease of scaling
- Utilize defensible clinical trial data to support calculations
Final Reconciliation Documentation
Once the final contract value and payments are agreed upon, memorialize the agreement in a final change order or closeout letter.
- A Final Change Order strikes the old contract and replaces it with the final budget.
- A Closeout Letter documents the final contract value rendered by the vendor.
Read the article